Stocks & Financial News
Breaking financial news 24/7 courtesy of TradingCharts.com Inc. / TFC Commodity Charts
Emerita Announces Positive IBW Pre-Feasibility Study Results Highlighting US$776 Million After-Tax NPV (8%), 23.51% IRR and 21-Year Mine Life
Iberian Belt West Project Pre-Feasibility Study Highlights
- Initial Probable Mineral Reserve of 23.4 million tonnes at 2.30% zinc, 1.13% lead, 0.45% copper, 53 g/t silver, 1.07 g/t gold
- Updated Mineral Resource Estimate reflects a 37% increase in Indicated tonnage and a 46% increase in Inferred tonnage compared to the 2025 MRE
- After-tax NPV (8%) of US$776 million and IRR of 23.51% in real terms
- After-tax payback period of 1.9 years from the start of production
- Initial capital cost of US$567 million including contingency
- Life-of-mine of 21 years with an average annual run of mine production of 1.2 million tonnes per year
- Conventional flowsheet producing four saleable concentrates of precious metals-bearing pyrite, zinc, lead and copper
- At achieved capacity, IBW is expected to produce average annual concentrate production of 43,489 tonnes of zinc concentrate, 26,120 tonnes of lead concentrate, 10,633 tonnes of copper concentrate, and 694,620 tonnes of pyrite concentrate on a dry metric tonne basis
- Precious metals-bearing (Au, Ag) pyrite concentrate with a high sulphur grade, the value of which is significantly influenced by contained gold and silver and the sulphur content
- Opportunities to further optimize IBW identified in the PFS, including development and sequence optimization, potential resource and reserve additions, exploration of satellite or new deposits, and metallurgical optimization, each of which requires further study
- The PFS was prepared by SLR Consulting, including qualified persons with experience in the Iberian Pyrite Belt
Toronto, Ontario--(Newsfile Corp. - October 29, 2026) - Emerita Resources Corp. (TSXV: EMO) (OTCQX: EMOTF) (FSE: LLJA) (the "Company" or "Emerita") is pleased to announce the positive results of a Pre-Feasibility Study ("PFS") prepared in accordance with National Instrument 43-101 - Standards of Disclosure for Mineral Projects ("NI 43-101") for its 100%-owned Iberian Belt West project ("IBW") located in the Iberian Pyrite Belt, Huelva Province in southwestern Spain. Unless otherwise noted, all dollar amounts ($) are expressed in US dollars (US$).
Joaquin Merino, Emerita's President and CEO, comments "The completion of IBW's PFS is the culmination of 2 years of studies involving various technical disciplines including mining and process engineering, metallurgy, geology, environmental science and commodity marketing. The PFS demonstrates the technical and economic viability of developing IBW into a high-grade polymetallic underground mine in the Iberian Pyrite Belt at a pre-feasibility level of study and identifies opportunities to further optimize IBW. The Company remains committed to the sustainable social and economic development of the region where it operates for the benefit of all stakeholders and local communities."
Emerita's Executive Chairman, Joseph Belan, adds, "Before announcing the PFS results, Emerita implemented a thorough review process, which included a rigorous technical and financial review of the underlying assumptions, methodology and conclusions. A technical committee, consisting of two (2) independent members of the Board, was also established to provide additional oversight of the PFS results and optimization recommendations."
IBW is royalty-free, 100% owned, and hosts three high-grade polymetallic deposits (La Romanera, El Cura, and La Infanta), all of which remain open along strike and at depth. IBW is situated in the Iberian Pyrite Belt, widely regarded as one of the most significant volcanogenic massive sulphide-producing geological belts in the world. Emerita currently holds 15,023 hectares of land grants in the Iberian Pyrite Belt, including IBW which comprises 1,546 hectares. Emerita's additional land holdings in the Iberian Pyrite Belt provide further exploration opportunities in the region.
IBW benefits from existing regional infrastructure, including proximity to the Port of Huelva, established transportation routes and renewable energy infrastructure. Emerita believes these factors may help reduce permitting and development timelines, as well as capital requirements; however, permitting, development timelines and capital requirements remain subject to material risks, including environmental approvals, engineering, water management, community engagement, regulatory review, financing, procurement, construction execution and commodity-market conditions.
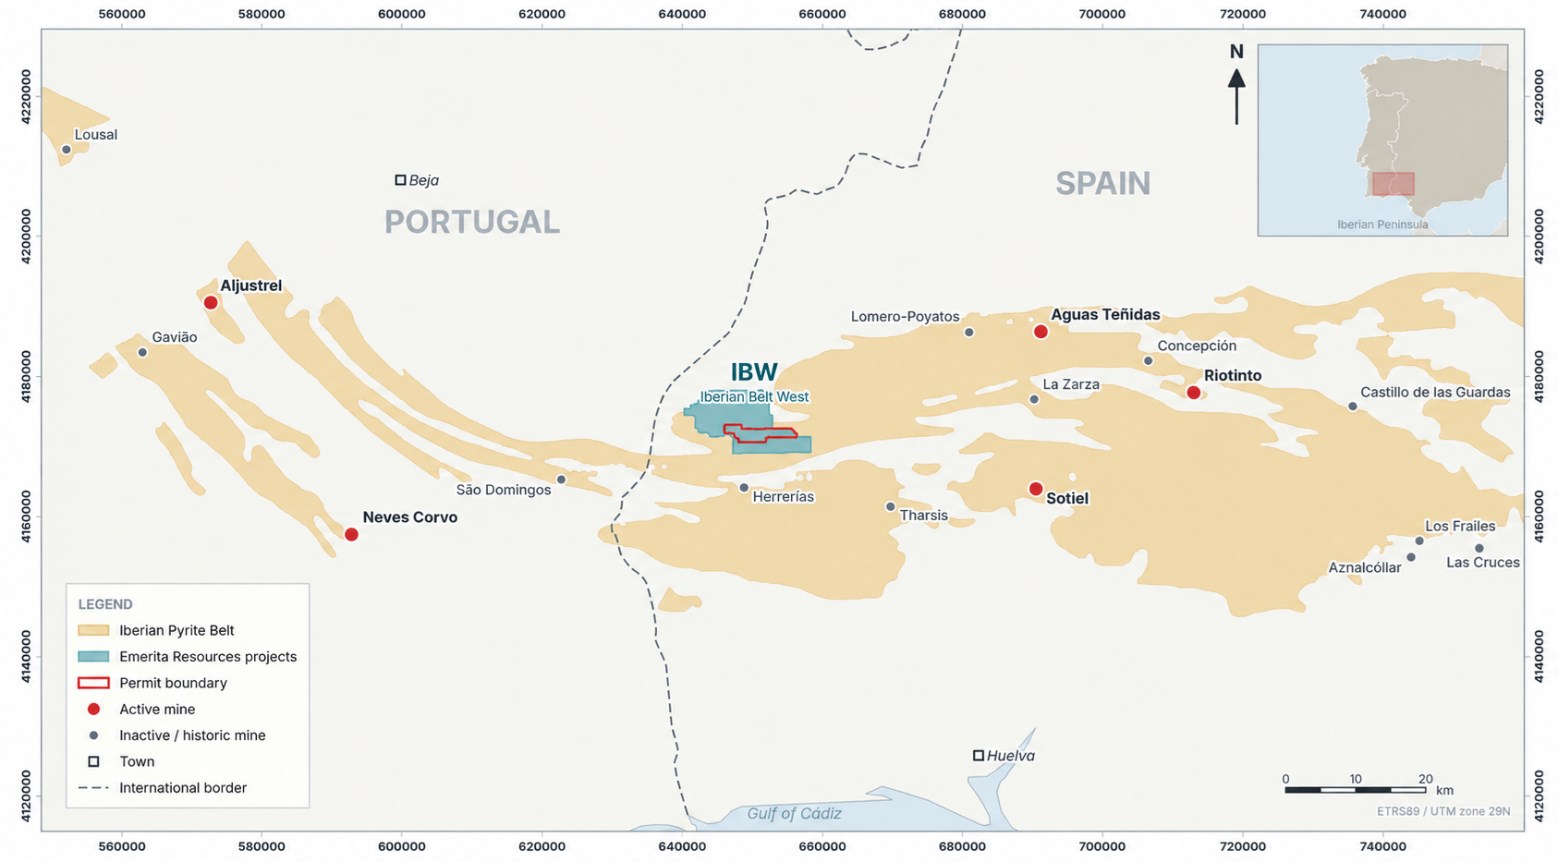
Source: Emerita Resources
Figure 1. IBW Location in the Iberian Pyrite Belt
To view an enhanced version of this graphic, please visit:
https://images.newsfilecorp.com/files/2209/321646_5cfbd225742a7b3b_001full.jpg
2026 Pre-Feasibility Study Results
The PFS supports an underground mining operation processing material from the La Romanera, El Cura and La Infanta deposits through a conventional flotation plant producing four saleable concentrates of precious metals (gold, silver) bearing pyrite, zinc, lead and copper. The PFS indicates positive project economics with significant leverage to sulphur, silver, gold, zinc, copper, and lead prices, a 21-year life-of-mine, and potential opportunities for further optimization. Table 1 shows the IBW PFS's economic and operational summary.
Table 1. Economic and Operational Summary of IBW Pre-Feasibility Study
| Table 1. Economic and Operational Summary of IBW Pre-Feasibility Study | Units | PFS (Base Case) |
| Long-Term Metal Price Assumptions | ||
| Copper Price | US$/t | 11,470 |
| US$/lb | 5.20 | |
| Lead Price | US$/t | 2,050 |
| US$/lb | 0.93 | |
| Zinc Price | US$/t | 2,980 |
| US$/lb | 1.35 | |
| Gold Price | US$/oz | 3,750 |
| Silver Price | US$/oz | 52 |
| Pyrite Concentrate Price | US$/t concentrate | 274 |
| Life-of-Mine Capital Cost Summary | ||
| Total Initial Capital Costs | US$ million | 566.7 |
| Sustaining Capital | US$ million | 279.5 |
| Closure Costs (Post-mine activities) | US$ million | 12.0 |
| Total Project Capital | US$ million | 858.2 |
| Life-of-Mine Unit Operating Costs (Year 1 to Year 21) | ||
| Mining Operating Costs | US$/t ore processed | 37.61 |
| Processing Costs | US$/t ore processed | 30.20 |
| Contact Water Treatment | US$/t ore processed | 3.52 |
| Capital Recovery Charge for Water Treatment Plant | US$/t ore processed | 6.06 |
| Mine waste / ATEM | US$/t ore processed | 0.15 |
| Tailings / IPS | US$/t ore processed | 0.53 |
| Paste Backfill | US$/t ore processed | 5.24 |
| G&A | US$/t ore processed | 2.97 |
| Progressive Rehabilitation | US$/t ore processed | 0.22 |
| Total Operating Costs | US$/t ore processed | 86.49 |
| Total On-Site Operating Costs, LOM | US$ million | 2,028 |
| Total Off-Site Costs, LOM | US$ million | 886 |
| Production Summary | ||
| Commencement of production | Year 1, following mine development in Years -5 to -1 | |
| Probable Mineral Reserve (Total ore feed to flotation) | Mt | 23.4 |
| Average Grade, Zn | % | 2.30 |
| Average Grade, Pb | % | 1.13 |
| Average Grade, Cu | % | 0.45 |
| Average Grade, Ag | g/t | 53.21 |
| Average Grade, Au | g/t | 1.07 |
| Average Grade, S | % | 33.85 |
| Plant Throughput (Nominal design) | ktpa | 1,200 |
| Life-of-Mine, Ore Processed | years | 21 (Years 1 to 21) |
| Recovery of Primary Commodity to Concentrate, Zinc concentrate | % | 78.65 |
| Recovery of Primary Commodity to Concentrate, Lead concentrate | % | 52.19 |
| Recovery of Primary Commodity to Concentrate, Copper concentrate | % | 41.48 |
| Recovery of Sulphur to Pyrite Concentrate | % | 93.62 |
| Recovery of Silver to Pyrite Concentrate | % | 87.63 |
| Recovery of Gold to Pyrite Concentrate | % | 88.42 |
| Concentrate Grade | 50.1% Zn; 26.76% Pb; 20.43% Cu; 50.67% S | |
| Concentrates Produced, LOM: zinc / lead / copper / pyrite concentrate | dmt | 845,652 / 514,778 / 213,080 / 13,573,653 |
| Average Annual Tonnage, Yr 2 to Yr 19: zinc / lead / copper / pyrite concentrate | dmt | 43,489 / 26,120 / 10,633 / 694,620 |
| Total Payable for Concentrates, LOM: zinc / lead / copper / pyrite concentrate | US$ million | 1,145 / 739 / 852 / 4,737 |
| Project NSR Contribution by Concentrate Type: pyrite / zinc / lead / copper concentrate | % | 66 / 14 / 10 / 10 |
| Summary of Base Case Economic Results | ||
| NPV (Real, After-tax) @ 8% | US$ million | 776 |
| IRR (Real, After-tax) | % | 23.51 |
| Payback Period from Production Commencement | 1 year, 11 months | |
| Payback Period from Initial Investment | 6 years, 11 months | |
| Earnings Before Interest, Taxes, Depreciation, and Amortisation (EBITDA), LOM | US$ million | 4,559 |
| Post-Tax-Free Cash Flow, LOM | US$ million | 2,664 |
| Profitability Index (PI) | x | 2.37 |
| NPV/Initial Capex Ratio | x | 1.37 |
 
Source: SLR
At higher exchange-traded metal prices consistent with September 2026 average spot prices for gold, silver, copper, zinc and lead (see Table 8), with the pyrite concentrate price held at the Base Case assumption, IBW's after-tax NPV (8%) increases to $1,019 million with an after-tax IRR of 27.13% and a reduced payback period after start of production of 1 year and 6 months.
While several processing routes were considered for the PFS, trade-off analysis indicated that additional metallurgical testing would be required for these routes to support a pre-feasibility level of study. As a result, the PFS adopts a conventional metallurgical flowsheet producing a saleable pyrite concentrate, with lower capital and operating cost inputs and a reduced tailings management footprint. Emerita has previously reported positive metallurgical results using alternative technologies. These and other available technologies may provide future optionality for IBW.
Unlike copper, zinc, lead, gold or silver, pyrite concentrate is not traded on a metals exchange. Pricing is negotiated under offtake or sales contracts and is typically based on the contained gold and silver (subject to payability) together with the sulphur content. The latter has value as a feedstock for sulphuric acid production, fuel in copper smelting and as a native sulphur source used in fertilizers and other industrial applications. The pricing adopted in the PFS for pyrite concentrate material is based on a market analysis that formulated long-term average pricing assumptions. These assumptions considered metallurgical specifications of IBW's pyrite concentrate in terms of quality and grade. Primary value drivers for pyrite concentrate are precious metals content and sulphur grade. Approximately 78% of gold and 47% of silver (contained within LOM ore feed) reports to the pyrite concentrate, which has a sulphur grade of >48%. The value of the pyrite concentrate contributes approximately 66% of the total NSR.
Mineral Reserves and Resources
An updated Mineral Resource Estimate ("MRE") prepared by SLR, effective July 17, 2026, reports a Mineral Resource of 26.1 Million Indicated Tonnes grading 2.27% zinc, 1.12% lead, 0.45% copper, 52.0 g/t silver, and 1.04 g/t gold, with 33.2% sulphur with an additional 9.9 Million Inferred Tonnes grading 2.13% zinc, 1.00% lead, 0.50% copper, 36.0 g/t silver, and 0.50 g/t gold with 22.7% sulphur. Table 2 shows the MRE with Net Smelter Return ("NSR") values for IBW and each of the deposits. The resource model includes attributes for economic commodity grades, penalty-element grades, classification, material type, and density.
Table 2. Mineral Resource Estimate for IBW as of July 17, 2026
| Deposit | Class | Tonnage Mt | Average Grade | NSR $/t | Contained Metal | ||||||||||
| Zn (%) | Pb (%) | Cu (%) | Ag (g/t) | Au (g/t) | S (%) | Zn (kt) | Pb (kt) | Cu (kt) | Ag (koz) | Au (koz) | S (kt) | ||||
| La Romanera | Indicated | 22.4 | 2.15 | 1.03 | 0.38 | 53 | 1.10 | 35.9 | 236 | 481 | 230 | 84 | 38,199 | 792 | 8,018 |
| Inferred | 6.6 | 2.02 | 0.84 | 0.49 | 33 | 0.57 | 29.6 | 192 | 133 | 55 | 32 | 7,090 | 120 | 1,952 | |
| El Cura | Indicated | 2.1 | 1.20 | 0.57 | 0.96 | 30 | 0.98 | 25.8 | 223 | 25 | 12 | 20 | 2,010 | 65 | 535 |
| Inferred | 0.9 | 0.98 | 0.42 | 0.74 | 19 | 0.62 | 18.7 | 165 | 9 | 4 | 7 | 556 | 18 | 168 | |
| La Infanta | Indicated | 1.7 | 5.25 | 3.00 | 0.73 | 63 | 0.25 | 6.7 | 228 | 87 | 50 | 12 | 3,316 | 13 | 111 |
| Inferred | 2.4 | 2.87 | 1.67 | 0.45 | 50 | 0.28 | 5.6 | 147 | 70 | 41 | 11 | 3,901 | 22 | 135 | |
| IBW | Indicated | 26.1 | 2.27 | 1.12 | 0.45 | 52 | 1.04 | 33.2 | 235 | 593 | 292 | 116 | 43,525 | 871 | 8,663 |
| Inferred | 9.9 | 2.13 | 1.00 | 0.50 | 36 | 0.50 | 22.7 | 178 | 212 | 100 | 50 | 11,547 | 161 | 2,256 | |
Notes:
| |||||||||||||||
 
Source: SLR
Underlying the MRE are calculated Mineral Reserves for the La Romanera, El Cura, and La Infanta deposits. These were calculated assuming underground long-hole open stoping (LHOS) mining methods, with cemented paste backfill or dry rockfill. Reporting is based on NSR cut-off values of US$69.30/t for La Romanera, US$79.20/t for El Cura, and US$85.30/t for La Infanta. These comprise a maiden Probable Mineral Reserve estimate of 23.4 million tonnes at 2.30% zinc, 1.13% lead, 0.45% copper, 53 g/t silver, 1.07 g/t gold and 33.85% sulphur, supporting the 21-year mine life. IBW's Mineral Reserves by deposit are shown in Table 3. Inferred Mineral Resources were not converted to Mineral Reserves and were treated as waste in the Mineral Reserve estimate.
The PFS mine plan and economic analysis exclude Inferred Mineral Resources. Inferred Mineral Resources are too speculative geologically to have economic considerations applied to them, and there is no certainty that any Inferred Mineral Resources will be upgraded to Mineral Reserves or included in any future mine plan. Emerita may evaluate additional drilling to assess whether portions of the Inferred Mineral Resources can be upgraded in future studies, but no production schedule, mine-life extension, capital-cost reclassification or NPV impact should be inferred from these Inferred Mineral Resources.
Table 3. Summary of Mineral Reserves for IBW, Effective July 17, 2026
| Deposit | Class | Tonnage Mt | Average Grade | NSR $/t | Contained Metal | ||||||||||
| Zn (%) | Pb |
|
|||||||||||||
Do not sell my personal information